Good incomes, young families, full lives. From the outside, many households look like they’ve got it all figured out. Photo by Seljan Salim on Unsplash.
Reading time: 7 minutes
Quick answer:
Many high earners in their 40s look successful from the outside, but their wealth isn’t growing in line with their income. The usual causes are lifestyle creep, large fixed costs (housing, cars, childcare), too little time, and avoiding the numbers altogether. High earners also tend to get a smaller share of their income back from state pensions, so they need more of their own savings to keep their lifestyle in retirement. The fix is simple, but not easy: find out where you stand, where your current path leads, and which changes would make the biggest difference to your financial trajectory.
The Gap Between Income and Wealth
Over the last years I’ve noticed something in common across several friends and colleagues. Many work in consulting, law, medicine, or engineering, or even run a small business. From the outside, most people would say they’re “checking all the boxes:” they enjoy solid incomes (well above average), young families, live in a good neighbourhood, and often have help at home, like a cleaner twice per week or a nanny helping out in the afternoons. They’re not going into debt to support their expenses; their lifestyle is fully supported by their income.
And yet, when nudged in conversations, a different picture comes up. While the income is there, many are starting to realize that their wealth isn’t building at the pace they’d expect. They have high-paying jobs but comparatively less to show for it: their savings rates are low, and, for many, a large share of their net worth sits in their house. When you dig in a little deeper, there is no real plan on how any of it will translate into a comfortable retirement. Early retirement is of course not even on the radar, despite them being arguably in a privileged situation.
This has nothing to do with intelligence. Some of them are very sharp, and there is a reason why they’ve landed high-paying jobs, in some cases with a lot of responsibility. I also empathize with this age group, who, if not already, is soon to join the “sandwich generation”: besides the responsibilities at work and busy lives with their young family, they are now starting to take care of their aging parents too.
Looking Wealthy Isn’t the Same as Being on Track
A high income tells you what comes in, not how much stays. Two households on the same salary could be decades apart from each other in terms of net worth and financial freedom, depending on how much they’re saving and investing.
Owning a house can also make things look better than they are. While home equity counts toward net worth, it can’t pay the bills in retirement unless you sell and downsize, or move somewhere cheaper. In our 30-year rent vs buy analysis, the buying household ended up with a solid net worth, yet still didn’t have enough income-generating assets to stop working before conventional age. This situation applies in particular to large cities with very expensive property relative to rents.
Here’s a simple, slightly uncomfortable test to measure your “years of freedom.” Take your invested assets, excluding your main home, and divide them by your annual spending.
Years of freedom = invested assets ÷ annual spending
For example, if you spend $80,000 a year and have $160,000 invested, your portfolio could cover roughly two years of your lifestyle. Investment growth makes little difference at low numbers. As the number grows, though, it’s true that it does more and more of the work, which is why around 25x is enough. This is the famous 4% rule, which establishes a guideline on how much you can sustainably withdraw from your portfolio for decades.
While there’s no perfect benchmark to tell you where you should be at, say, 45, if you’re in single digit years of freedom, you’re probably relying too much on a state pension. This little test is not meant to discourage anybody. On the contrary, there is still time to take action; you still have some room to maneuver.
A beautiful home says a lot about income, but very little about your savings rate or whether there’s an actual plan to sustain your lifestyle in retirement. Photo by DP Singh Bhullar on Unsplash.
Why Smart, Busy People Put Off Money Decisions
From my observations, these are usually the most common reasons people put off money decisions.
No time, no energy. It’s more than understandable. Work, kids, school runs, social plans, and, increasingly, ageing parents make it hard to find the headspace. Finding a couple undisturbed hours to take a proper look at your finances simply feels impossible.
Full effort at your job, very little effort for yourself. Many people take pride at putting large efforts into excelling at work, and it’s partially paying off: you have a “high-status” job and high income. Unfortunately, far less of that effort goes into a plan that will turn that income into assets. Yet it’s income-generating assets, not salary, that ultimately buy you control over your time, even long before retirement.
Lifestyle creep. Each raise is accompanied by a slightly larger flat, a nicer car, or more help at home. None of these decisions are “wrong” in isolation; the problem is that if spending always rises as fast as income, the savings rate stays flat or even falls. Therefore, it’s absolutely possible to earn more, and still lock yourself into a worse financial situation.
The “big three” lock you in early. Housing, transport, and food are usually the largest costs in most household budgets, and for families, childcare or school fees are often high up there. Housing and cars in particular tend to be decided once, but contribute to shape your saving rate for a very long time. They’re also usually the hardest to undo.
The ostrich effect. Researchers have found that investors look up their portfolios more often when markets are rising, and look away when they’re falling (this applies to me 100%). Personal finances work the same way: when we suspect the news may not be good, we avoid looking under the hood and procrastinate. Of course, if you never take a proper look at your financial trajectory, nothing will feel wrong until it’s too late to take action.
The conversation you’d rather not have. Sometimes we’re not afraid about facing the numbers themselves, but more about the conversation you’ll need to have with your spouse. Sometimes these are difficult feelings to address, and so it feels easier to postpone.
The “later” logic. Take your choice: once the kids are older; after the promotion; when work calms down; when this month’s busyness settles. In the meantime, though, the years pass and the possibility of investments compounding in your favor is slipping away little by little.
Three 40-Year-Olds, Three Very Different Futures
Let’s make this concrete with a few examples. Consider:
A household with two professionals earning $140,000 a year after tax
They spend $130,000 of it, and save $10,000 per year (a 7% savings rate)
They’re 40 and have $75,000 invested, plus their home
Let’s assume 7% real returns from their investments and a withdrawal rate of 4–5% (how much they can withdraw from their portfolio in retirement)
For simplicity, let’s leave pensions out for now
We use our FI calculator for the calculations
We have one starting point, but three different profiles and courses of action to consider: the “Drifters,” the “Gradual Fixers,” and the “Fast Fixers.” Let’s see how each strategy performs in terms of timeline to retirement.
The Drifters, for one of the reasons mentioned above, do not take action and continue along this 7% savings trajectory for the rest of their careers. Without pensions and Social Security, it would take them another 40 years to reach Financial Independence on their portfolio alone, reaching it at age 80. At age 67, their portfolio would be around $1,200,000, allowing them to spend about $48,000-$60,000 per year. They’d be in big trouble, because state pensions in most countries would be unlikely to plug the $70,000-$82,000 shortfall in covering their annual expenses.
Next come the Gradual Fixers. They understand that the problem here is their low savings rate, and, given their responsibilities, they decide to implement a gradual approach that will enable them to adjust it without feeling the pain in the short term. They implement the 1% Savings Method for a year and increase their savings rate by 1% point each month. On a month per month basis, they barely notice the adjustment, but after a year they’re now at a 19% savings rate, which they then sustain for the rest of their careers. This adjustment also changed their annual spend to $112,000 per year.
This “small change” would enable them to reach Financial Independence with their portfolio alone in 29 years (close to age 70). Notice that this is already 11 years faster than in the first story. At age 67, their portfolio would be around $2,300,000, enabling them to spend around $92,000-$115,000. Adding any meaningful state pension into the mix, the small adjustment made in their 40s would even allow them to retire early, perhaps 3–5 years earlier, depending on the size of that pension.
Finally consider the Fast Fixers, who literally double down on the previous plan, and decide to raise their savings rate by 2 percentage points per month. On a monthly basis this means finding about $233 extra to save each month (raising their monthly savings from $833 to about $1,066 in the first month, on an after-tax income of $11,667). Of course, this plan is tougher to implement, but the Fast Fixers dislike their job and are motivated by the prospect of more freedom and an early retirement in good health.
This change would enable them to reach Financial Independence with their portfolio alone in 22 years (age 63), about 7 years earlier than the previous case, with a $2,400,000 portfolio. Like in the previous case, given any meaningful state pension, they could also consider retiring a few years before that, perhaps even in their late 50s: their nest egg would bridge the gap with a slightly higher withdrawal rate until they reached the age they could use their state pension.
The main takeaway here should be that the difference between the three households isn’t income or intelligence. It’s simply making a decision at 40, and sticking with it. As observed, the cost of waiting is not only measured in a lower net worth, but also in years of work.
There’s also one final idea to consider. In many countries, state pensions replace a smaller share of income for high earners, because of contribution caps or formulas that tend to favor lower incomes. Although the details vary per country, a low earner with a modest lifestyle can be better placed than a higher earner in the sense that they may not only have a higher savings rate, but also a pension that is closer to what they actually spend.
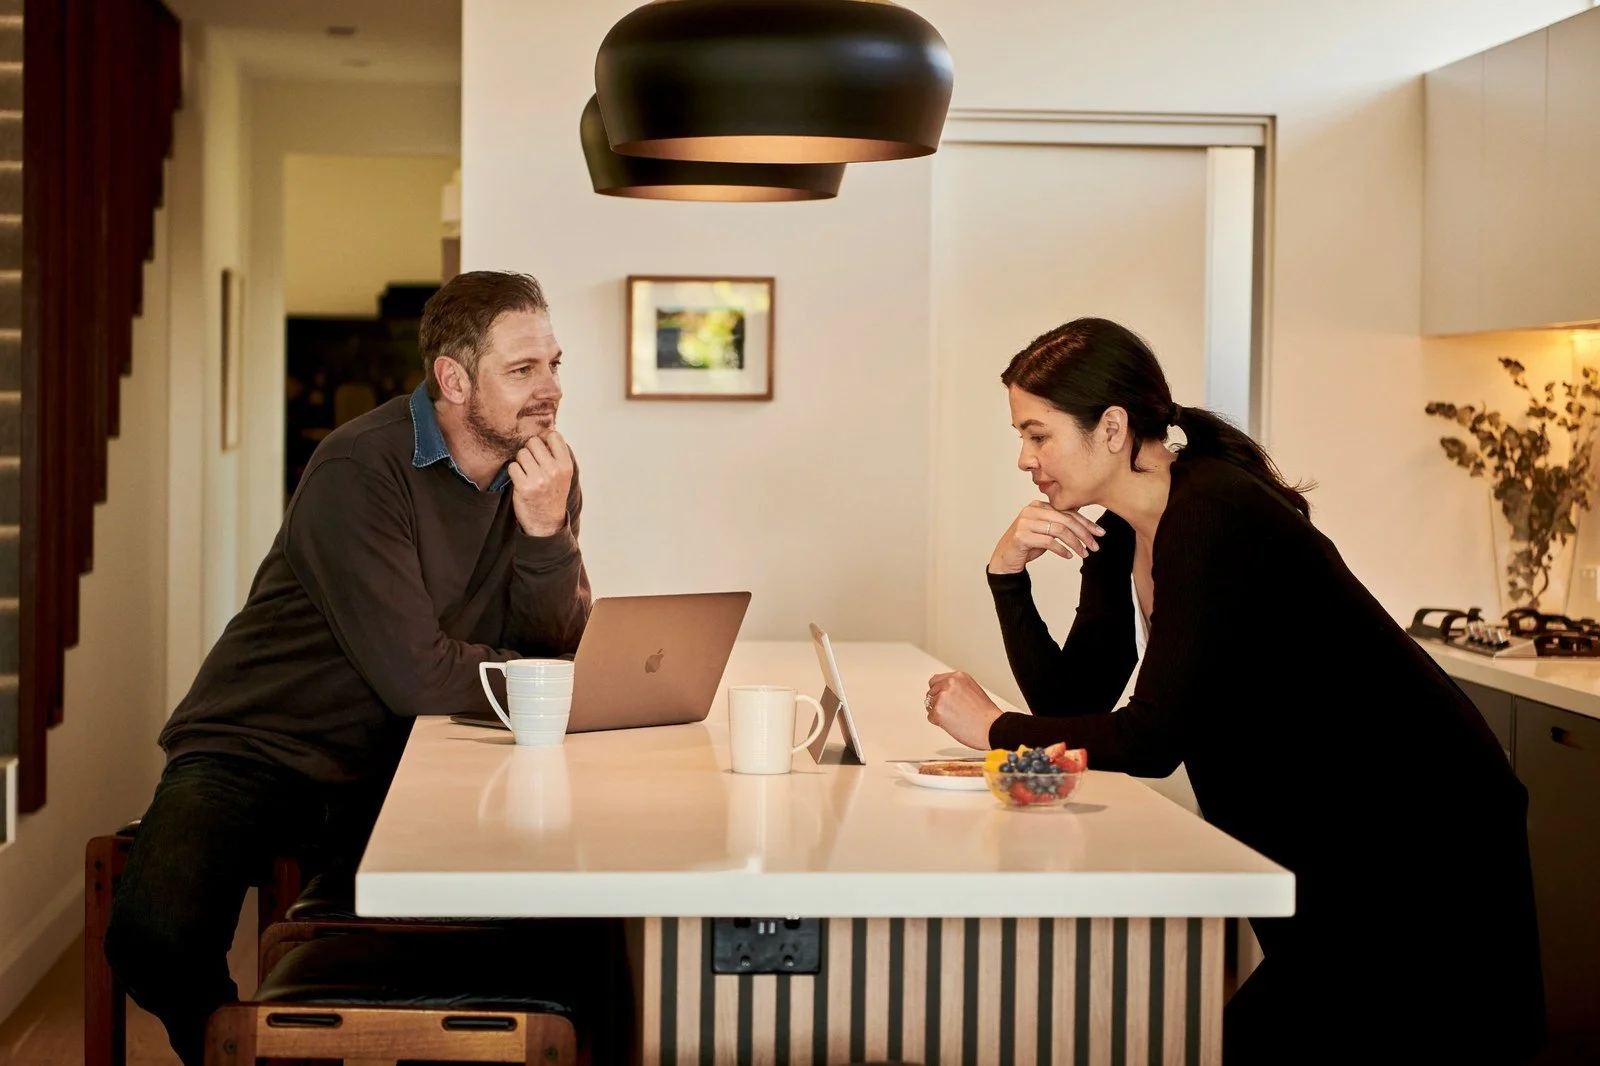
The hardest step is rarely the solution itself. It’s sitting down together and taking an honest look at the numbers. Photo by Docusign on Unsplash.
Where Do You Actually Stand?
The good news is that many folks in their 40s may not need a dramatic change in their finances. Even a moderate increase in your savings rate can move things quickly, as the Gradual Fixers example showed. And the advantage, of course, is that with a high income there’s usually a lot more wiggle room to raise it without having to touch the essentials.
Factor in a pension, a flexible withdrawal strategy, and perhaps downsizing later on, and stopping work somewhere between 57 and 62 can still be realistic, even if you’re pursuing FI as a late starter.
How you invest matters too. As we showed in our article “The Bond Trap”, at lower savings rates, an overly cautious portfolio may be adding years to your retirement timeline.
The hardest part for those with busy lives is not implementing the solution. The solution is easy. What’s difficult is taking the time to sit down, look at your numbers, and make decisions.
And if you need help with that, that’s exactly what I do with my 1:1 FI Strategy Sessions. We model your real situation in ProjectionLab: your spending, savings rate, investments, pension, house, the cost of kids, and anything else on your mind. Once we set your baseline trajectory and timeline to retirement, we look at different levers that could realistically help you stop working sooner.
If you’d rather start on your own instead, be sure to block a few hours in your calendar this week, pull your last 12 months of bank statements, and figure out, as a first step, your savings rate and financial trajectory. A few hours of analysis now may save you years of work later. Our FI checklist may be helpful too for those who want to figure it out by themselves.
Next steps:
👉 Work out your timeline to retirement with our FI Calculator (free, email unlock)
👉 Raise your savings rate without overhauling your life: The 1% Savings Method
👉 Starting later? FIRE for Late Starters: The Real Math of Starting at 40, 45, or 50
👉 Work with me: 1:1 FI Strategy Sessions
👉 Subscribe for free FI tools and monthly insights. One-click unsubscribe
Disclaimer: I’m not a financial, tax, legal or investment adviser, and nothing here is financial, tax, legal or investment advice. This article and my 1:1 sessions are educational and for informational purposes only. All modeling (including any tax scenarios) is illustrative and informed by software, not a substitute for professional advice. All decisions are your own.
Frequently Asked Questions (FAQs)
-
Usually because spending rises with income. Lifestyle creep, large fixed costs like housing, cars and childcare, and a lack of time to plan keep the savings rate low, even on a high salary.
-
There’s no single number, but going from under 10% to 20% or more can bring retirement forward by a decade. What matters most is raising it steadily and keeping it there.
-
No. With 20+ years of compounding ahead, a 40-year-old who raises their savings rate today can still realistically stop working early, especially once a pension is factored in.
-
A quick check is to divide your invested assets (excluding your home) by your annual spending. Financial independence is reached at roughly 25 times your spending. If you’re in single digits in your mid-40s, it’s worth looking at your plan in detail.
Join readers from more than 100 countries, subscribe below!
Didn't Find What You Were After? Try Searching Here For Other Topics Or Articles: